LPs Starting to Look for Bids
April 11, 2025
In the wake of President Donald Trump’s decision to implement reciprocal tariffs on dozens of countries, the secondary market for private equity fund stakes has been thrown into a state of heightened uncertainty. Within days of the announcement, asset manager Hamilton Lane experienced a surge in activity, with limited partners (LPs) reaching out in droves to assess the market’s temperature. “There’s been a ton of inbound conversations,” said Keith Brittain, who oversees the firm’s secondary business. “Limited partners are calling us, asking us if we’re still active buyers and what the pricing is for these funds.”
This sudden spike in interest is being felt industry-wide, as pensions, endowments, family offices, and foundations begin reevaluating their portfolios and exploring the possibility of offloading illiquid investments on the secondary market. Distributions from private market fund commitments have already been sluggish over the past few years, and this week’s plunge in the stock market further dampened optimism around near-term IPOs and other exit opportunities—reducing returns to LPs and increasing liquidity concerns.
According to Brittain, many of the calls are preliminary, with LPs simply testing the waters through “what-if” scenarios. But the volatile environment has made pricing extremely difficult. Most secondary buyers, including Hamilton Lane, are stepping back to allow private equity managers time to reassess the effects of tariffs and public market swings. Despite a 90-day pause on the tariffs providing some clarity, the market remains too uncertain for buyers to confidently determine the true value of LP stakes. “This is a period of price discovery between buyers and sellers, which leads to a widening bid-ask spread and ultimately fewer completed transactions,” said Justin Lux, managing director at FS Investments. He noted that upcoming deals would likely be priced off Q4 2024 valuations, once firms have had time to adjust.
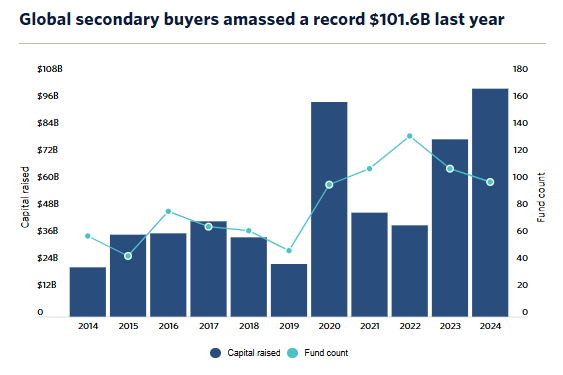
Steven Patrick Murphy, Portfolio Manager at Q76 Capital, stated “As soon as these secondary funds get more spooked and won’t provide bids to any of these LPs for their stakes is when the GPs will start transacting.” In other words, only once the buyers retreat will general partners (GPs) be forced to get real about current asset values and liquidity needs.
Beyond pricing, many secondary buyers are also wary of tariff-related risks. Chris Lawrence, managing partner and founder of Labyrinth Capital Partners, compared investing in companies with significant supply chain exposure under current conditions to “catching a falling knife”—a term familiar from the 2008 global financial crisis. While he believes volatility will drive more sellers into the market and potentially increase transaction volume in the short term, he doesn’t foresee widespread fire sales—except possibly among assets heavily tied to Chinese supply chains. “For those with China exposure—that may be a different story until that situation is further clarified,” Lawrence warned. “More unknowns mean more risk for those companies.”
Ultimately, with buyers hesitating and valuations in flux, the secondary market has entered a cautious holding pattern, awaiting greater certainty before dealmaking can resume in earnest.
Steven Patrick Murphy II
[email protected]